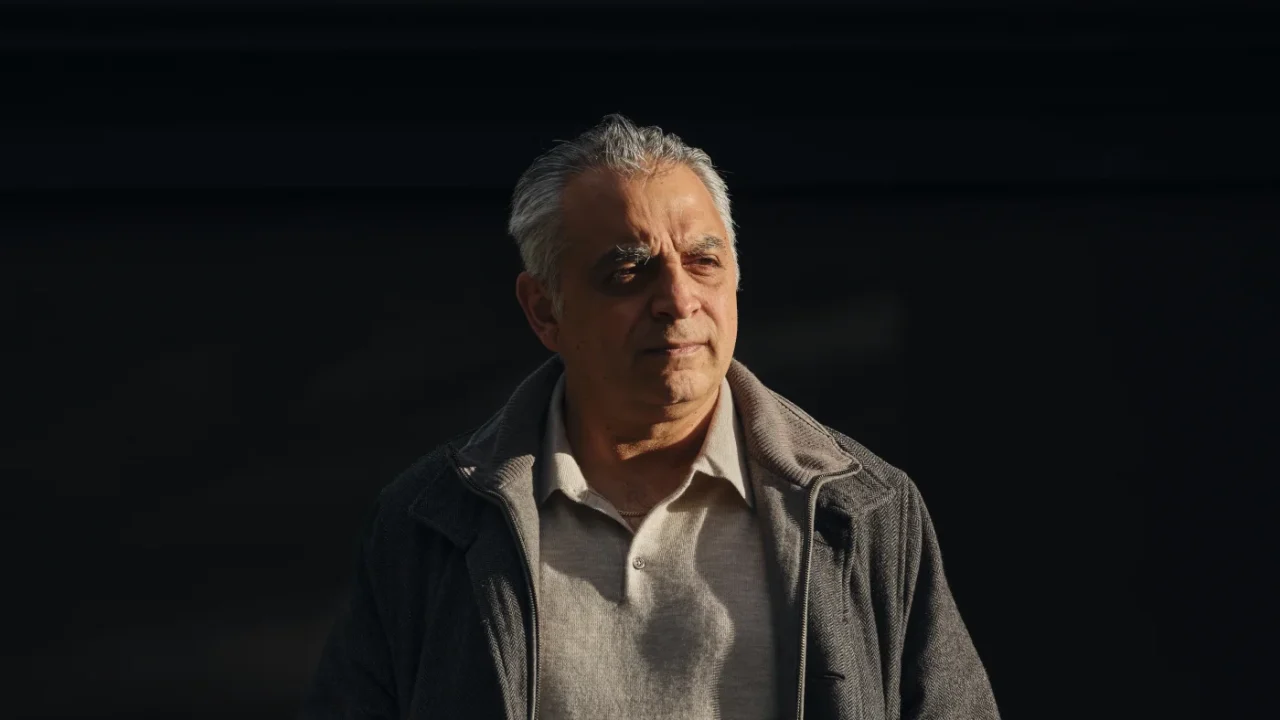
Vahe Shahinian, a Los Angeles-based event producer, is suing funders after a financing deal he believed to be a traditional line of credit resulted in overwhelming debt and business hardship. The lawsuit, which has been in progress for seven years, marks one of the first cases of this nature to head toward trial, according to NPR.
Shahinian’s company, It’s My Seat, was thriving in 2019, with ticket sales nearing $5 million annually. After a major credit card issuer discontinued a favorable merchant financing program, Shahinian struggled to secure $200,000 in funding for an upcoming tour within two weeks. He initially turned to merchant cash advances (MCAs), paying back nearly $400,000 on a $250,000 advance.
Subsequently, a broker offered Shahinian a $750,000 line of credit at an annual interest rate of just under 9%. The condition required him to accept one-third of the total sum immediately and make daily payments of $3,600 for 30 days before accessing the remainder. Shahinian states he was led to believe this was a standard qualification test by Wall Street-based firm EIN Cap. However, the subsequent release of the remaining credit never occurred, leaving him in a state of daily payments without the promised capital.
Legal experts describe this tactic as “carroting,” a bait-and-switch strategy where lenders dangle the promise of low-interest loans to secure borrowers into high-fee merchant cash advances. Because MCAs are structured as purchases of future sales rather than traditional loans, they generally escape standard lending regulations and licensing requirements. Industry data suggests MCA fees can equate to annual rates between 25% and 200%.
Shahinian continued paying the daily installments for years, depleting his savings and eventually facing debt collection threats. His attorney, Shane Heskin, notes that such schemes often target first-time business owners and immigrants, with the volume of similar complaints rising significantly.
EIN Cap has argued in court that it provided a merchant cash advance as per the agreement, placing responsibility on the brokers for any misrepresentations made during the sales process. The trial date for the case has been delayed multiple times, but the dispute continues to highlight the regulatory gaps in the rapidly growing MCA industry.
The fact that they call it a purchase of future sales is so clever and scary.
Seven years is insane. How does anyone function with that kind of financial pressure hanging over their head?
I always wondered why merchant cash advances get away with such high fees. This lawsuit might finally change that.
This ‘carroting’ tactic is disgusting. These lenders prey on people when they are desperate for quick cash.